

CNN invited me on-air on September 28 to discuss record-high diesel prices, high costs for everything else, and the outlook for housing with mortgage rates at 7%. Here’s the clip. Takeaways follow, including a brief look at the history of mortgage rates and how we compare now.
Statement of the obvious to say gas and diesel prices are way too high and it’s a disastrous outcome of Trump’s war with Iran. A more competent president would have anticipated this.
Nobody needs to tell Americans how much extra it costs to fill up their tank. Before the war, a 15-gallon fill-up cost $45. Now it costs $68. So far, pricier gasoline has cost the typical household more than $500, according to the Watson Institute at Brown University.
[Believe it or not, the economy is strong]
Most people don’t buy diesel, which makes it harder to gauge the cost crunch for a typical family. But record high diesel prices raise the cost of planting, harvesting, and transporting food, and shipping most consumer products. Higher diesel prices have cost the typical household another $412, according to the Watson Institute. Total cost of the Iran war: $915 per household, and counting.
Interest rates are rising for a variety of reasons, with the average mortgage rate now above 7%. How painful is that? Let’s look at the history of mortgage rates.
A 7% mortgage rate isn’t unusual. In fact, it’s close to the historical average, if you go back decades. What has been unusual is the last 18 years, with rates much lower than usual, largely thanks to Federal Reserve monetary stimulus measures that began with the Great Recession in 2008.
So we’re now reverting to more normal interest rate levels. But this is happening with home prices that are unusually high.
When mortgage rates fall, home prices tend to rise, since cheaper mortgages boost demand and that sends prices higher. There was a dramatic jump in prices during the Covid pandemic that started in 2020, mainly because the Fed slashed interest rates to record lows. You can see the dynamic in both charts, starting in 2020: Rates plunge, prices soar.
[The Weekly WTF: America’s worst TV channel]
As mortgage rates have been rising, home prices have begun to drop—a little. But the market is still way out of whack and is likely to stay that way for a while. The biggest problem is there’s not enough lower-priced housing. Local zoning rules and other regulations make it hard to build. Developers would rather build mansions with high profit margins than entry-level homes or multifamily units.
Trump’s policies have made the housing problem worse. His tariffs have raised the cost of lumber and other building materials at a time when homes are already pricey. His deportation policies have thinned out the construction workforce and pushed labor costs higher. Congress passed a law over the summer meant to create incentives for more affordable housing, which might help. But it will take years.
[5 things to expect if Democrats win in December]
The Pinpoint Press has been arguing that it’s time to rethink the American Dream. Home ownership has been the main way ordinary families built wealth for decades. But there are other ways to get ahead. Shrewd investing is easier than ever, with low transaction costs. You can start an investment account with a couple hundred dollars. Financial investments carry risk, but that declines the longer your time horizon. And you can invest in ways that limit your risk to whatever you’re comfortable with.
The amount of financial wealth in the United States now exceeds the amount of real-estate wealth. The richest Americans own most of those financial assets—but there’s no rule that says only the wealthy can own stocks and other assets. If you think owning a home is the simplest or fastest way to build wealth, you might be missing out.
Enjoy a cartoon.
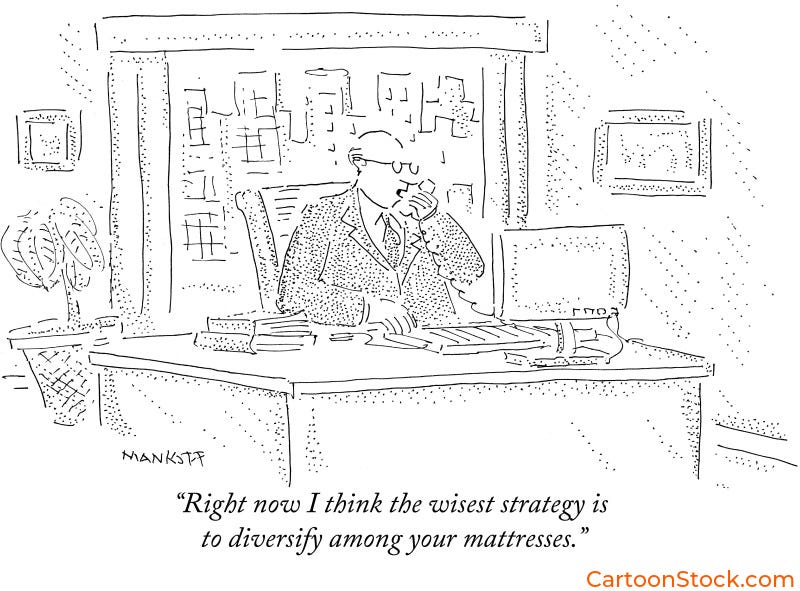
You can order this cartoon👆 and play cartoon-themed puzzles and word games at CartoonStock.com.
The market is a good place to be in right now if you are young enough but not so much if your on social security and,nothing else.We have some money saved up for a rainy day but, sometimes i think did we save enough.If you get in the market there are way's to make it work for you.You can do it with as little as fifty buck's a month and, it can make you a fortune.
LOVED THE CARTOON!!! Hahaha!
That chart of average house prices over the decades... made me review a spreadsheet I keep and update once a year (yes, I've been told I need to get a life) to look at the inflation rate (CPI-U) for our county, the rate of increase of our house "price" (average of Zillow and Redfin estimates), and our house's valuation by our county (for property tax purposes) since our purchase around 21 years ago -- each expressed as a CAGR (compound annual growth rate) over these two decades. As of mid-2026, the three figures respectively are: 2.9%, 3.6%, and 1.6%. So our house price (private valuation) has been running ahead of inflation... a 0.7% difference per year over 21 years adds up, and our house valuation is cumulatively 15% ahead of inflation! This is a real hardship for new home buyers. It is also true that the average home size and amenities have changed dramatically over the period covered by the graph you shared, but home ownership is definitely getting out of reach for more people. Your idea of biding time and investing in a diversified and riask-appropriate manner is a very sound alternative for building wealth. I'm sure that by any measure you'd be way more than 15% ahead of inflation that way! Maybe even a factor of 2 or something given what the stock market has done in the last 2 decades even accounting for the "bear markets" associated with the GFC (2007--2009), COVID (2020), and the post-COVID inflation-related market bloodbath in 2022.